
Summary
- CSX sold off hard on its Q2 earnings and cut to its revenue forecast.
- CSX changed its forecast from +2% revenue growth to -2% revenue growth.
- The market asked few questions and pulled the trigger.
- Diving into the earnings call that seems a bit premature.
- Looking for a portfolio of ideas like this one? Members of Special Situation Report get exclusive access to our model portfolio. Get started today »
CSX (NASDAQ:CSX) posted a huge decline yesterday which incited me to review this company again. It reportedly declined because of weaker-than-expected Q2 earnings and the cut in its full-year revenue forecast. I've recommended CSX to subscribers in March 2018 and wrote a public piece in May 2018. The basic idea behind my investment at the time relied on
- CSX having the attention of an activist
- Precision railroading being implemented
- Underestimated tax tailwinds
CSX has done quite well since those articles. It crushed the S&P 500 total return index, but to be fair, it only beat the Dow Jones U.S. Railroad index by a slight margin.
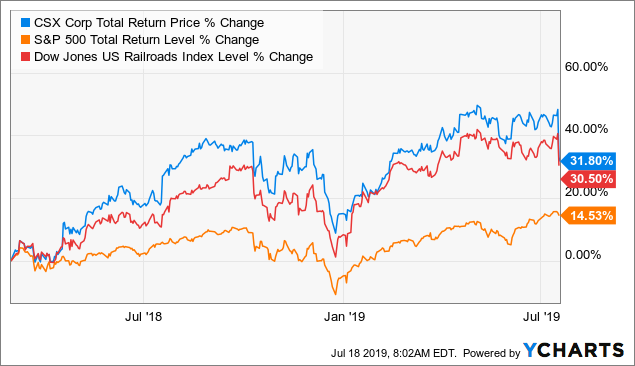 Data by YCharts
The first thing I'll do is review the earnings call to see what exactly is sparking this sell-off and how bad it really is. Then, I'll take a look at the valuation here and, finally, look if the main idea is still intact. Let's dive into the earnings call. Emphases are mine.
First, I want to note some of the positives as per CFO Kevin Boone:
...Moving to expenses. Total operating expenses were 3% lower in the second quarter, reflecting continued strong efficiency gains.Labor and fringe expense was 3% lower, driven by a 5% reduction in headcount combined with favorable incentive compensation expense. These savings were partially offset by inflation and other items...
...Active locomotive count declined more than 300 locomotives, down 11% year-over-year. Smaller fleet combined with fewer cars online and freight car repair efficiencies helped drive a 6% year-over-year reduction in our mechanical workforce....
Lower active locomotive count drove savings in materials and contracted services.
Operating expenses decreased, and the active locomotive count is down in a big way. The precision railroading playbook keeps being executed on and it is delivering. And, there's more to come:
Closing out the P&L. As Jim highlighted in his opening remarks, CSX delivered operating income of $1.3 billion, record operating ratio of 57.4% and earnings per share of $1.08, representing improvements of 2%, 120 basis points and 7% respectively. We continue to see significant opportunities to drive efficiencies across every aspect of our business.
Boone even dives into some of the specifics. It becomes much more believable and likely when the management team actually put practical examples on the table. Often they don't, for competitive reasons, or to give themselves some flexibility in the future.
Overtime also remains a significant opportunity with a particular focus on its mechanical and engineering. There are multiple emphases across our business functions where overtime as a percentage of straight time is well over 20% and in some cases exceeding 40%.
He also goes on to mention fuel efficiency, train speed and dwell and G&A. Then, let's look at the things CEO Foote said that seem to have scared the market so much:
Jim Foote
Thanks Kevin. Turning to Slide 13, I want to wrap things up by discussing our guidance for the year. We started this year expecting revenue to be up approximately 1% to 2%. Both global and U.S. economic conditions had been unusual this year to say the least and have impacted our volumes. You see it every week in our reported carloads. The present economic backdrop is one of the most puzzling I have experienced in my career.
With natural gas prices expected to continue to impact both domestic and export coal, intermodal is showing little seasonal recovery and many of our industrial customers volumes continuing to show weakness with no concrete signs of these trends changing; and adding in the impact on crude-by-rail shipment of last month's Philadelphia refiner explosion, we are now expecting revenues to be down 1% to 2% for the full year.
This is a 4% change in revenue growth expectation. That's a big change in this business. On top of that, it went from positive to negative. I think people dislike that more than positive growth disappointing. But let's go deeper and see what context he provided along with this guidance:
We are not necessarily being pessimistic about the second half of the year. But in these launches we need to adjust guidance, we're just setting out the obvious. This outlook is based on a current business levels and there is upside to this forecast as conditions improve in the second half.
Later, Foote adds even more color to that saying he's obligated to update guidance when it changes. Since he had to change guidance and doesn't want to guide down quarter over quarter, he more or less decided to take it down in a big way now. I'm actually pretty nervous about the economy, or especially the market, but this sounds like it maybe isn't as bad as it looks. Foote also has a secondary motivation for the guide down:
plus it gives us the ability internally to say, hey guys, this is the new norm, let's tighten our shoes, let's get to work and we're going to achieve our targets.
As he is overhauling operations and changing cost structures, there will be more buy-in when times are tough. When everything is well, it is much harder to take the tough measures necessary for the future.

